Paying for a Pool: Financing Options in Texas
Three lenders, fixed terms of 2 to 20 years, and a few budgeting habits that keep a pool loan from becoming a headache.
October 14, 2026 · 4 min read
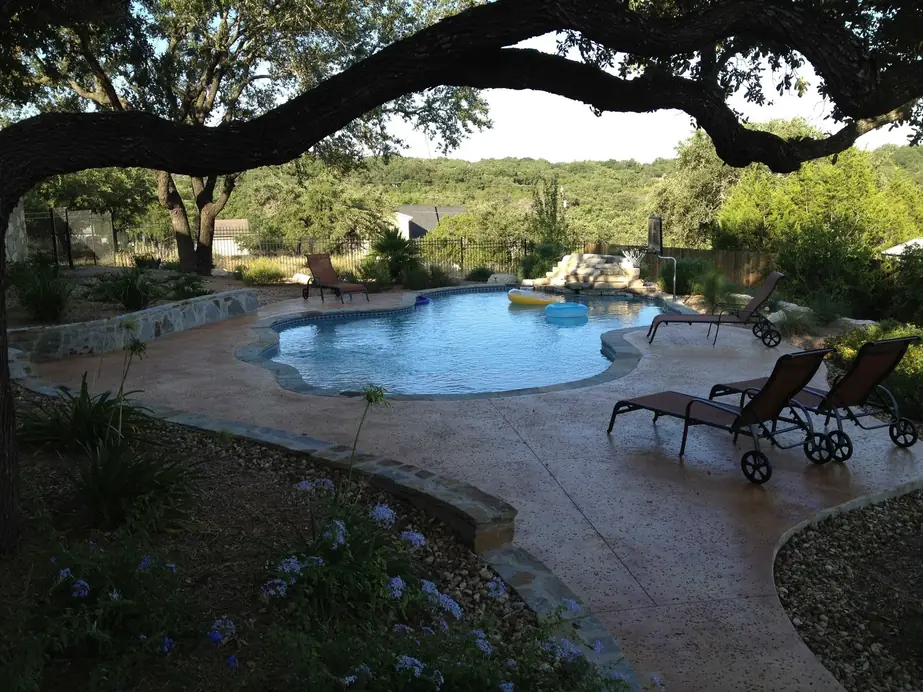
Most of the families we build for finance at least part of their pool. That's normal, and it can make good sense when fixed rates are competitive. This guide covers the three lenders Pools Unlimited works with, how the process runs, and some general advice for budgeting a pool. Rates and terms change often, so treat everything here as a starting point and confirm current details with the lender directly.
The three lenders
We've worked with these lenders for years. Typical terms run 5 to 20 years, fixed-rate. You apply directly with the lender you choose, and we help you pull together the project numbers they ask for.
- Lyon Financial. A lender that focuses on dedicated swimming pool loans. Terms run 5 to 20 years, with financing up to $150,000, and there are zero dealer consulting fees.
- LightStream. Unsecured loans for pool construction and landscape, with terms of 2 to 12 years and no prepayment penalty. It's aimed at borrowers with excellent credit.
- LendingClub. Digital personal loans with fixed terms of 2 to 7 years. It suits smaller remodeling projects or filling a gap in a larger construction budget.
Each one has different strengths. A very large new build and a smaller remodel call for different tools, and the right pick depends on the amount, the length of term you want and how you feel about secured versus unsecured borrowing. If you're not sure, ask each lender what they would offer for the same project number and compare the answers side by side.
How the process runs
- Estimate. Get a detailed proposal and design first, so you know exactly how much to finance.
- Rates. Fill out a short online application with the lender. The application is quick, about 2 to 5 minutes, and shows your rate options.
- Secure. Once approved, funds typically arrive within 1 to 5 days, either to your account or released for stages of construction, depending on the lender.
- Build. With the money in place, the construction team pulls permits, schedules excavation and starts the 4 to 18 week build.
The order matters. You can't sensibly borrow before you know what the pool costs, and on a Hill Country lot the price depends on rock, slope and access that only a site visit can judge. That's why the first step is the estimate, not the loan application.
What a monthly payment might look like
Our own cost guide gives one example: a $150,000 pool financed over 15 years at a competitive fixed rate runs roughly $1,100 to $1,300 a month. Pre-qualification with our lending partners doesn't affect your credit score, so it costs nothing to see what your own rate would be. Think of that example as an illustration of scale only. Your numbers will depend on the lender, the term, your credit and the loan amount, and none of those are things we can promise for you.
General advice for budgeting a pool
None of this is financial advice for your specific situation, and a lender or advisor you trust can speak to your numbers better than we can. These are habits that tend to help.
- Borrow against a fixed price. A fixed-price contract means the loan amount doesn't have to drift upward halfway through the build.
- Compare total cost, not only the payment. A longer term lowers the monthly figure but usually means more interest paid overall. Ask each lender to show both.
- Check for prepayment penalties. If you might pay the loan off early, you want to know up front whether that costs you.
- Plan for the running costs. A pool brings ongoing expenses for electricity, chemicals and upkeep on top of any loan payment. Ask for equipment efficiency details during design.
- Decide on add-ons before you borrow. Adding a spa or ledge after the build usually costs more, so settle the feature list first and finance the whole scope once.
- Ask your insurer and your county appraisal district what a pool does to your coverage and your taxes. The answers differ by property, so get them in writing from the source.
Finance now or wait and save?
Plenty of people ask whether they should wait and pay cash. That depends on your savings, your other goals and what rates look like when you apply. Waiting has its own cost, since you don't get the years of use in the meantime, while borrowing adds interest. Neither is wrong. Many owners split the difference with a larger down payment and a smaller loan, which is worth asking each lender about.
Start with a number
A budget built on guesses falls apart. Before you spend time comparing lenders, get a fixed-price number for your actual lot. That number tells you how much to borrow, and it gives each lender the same project to quote against.
That begins with a free on-site visit, with no obligation. Call Pools Unlimited at (830) 980-5051, and once you have a real project number you can compare current lender terms with confidence.
Pools Unlimited, Inc., (830) 980-5051
Call (830) 980-5051More articles
How Much Does a Gunite Pool Cost in the Texas Hill Country?
A straight answer on what a custom gunite pool costs here, and why the same pool can land at very different numbers on two different lots.
How to Design a Pool for a Sloped or Rocky Hill Country Lot
A hillside lot is harder to build on, and it also makes room for the most dramatic pools, if the engineering is done right.